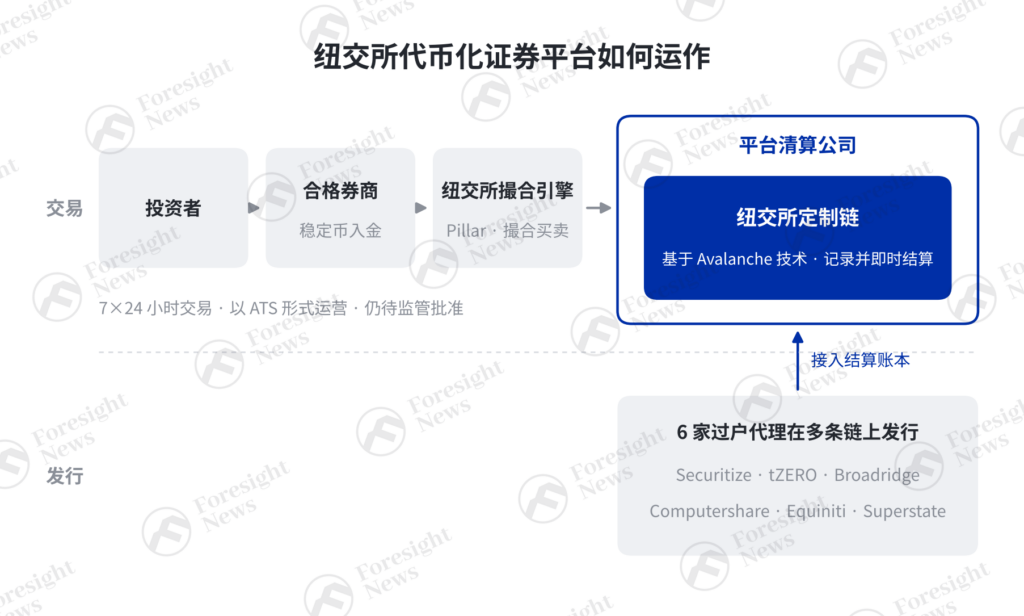
The NYSE’s planned round-the-clock tokenized-stock platform would use Avalanche technology to settle trades, according to details reported on November 9, 2026. The distinction matters: the proposed settlement ledger is a custom, permissioned chain, not Avalanche’s public C-Chain. The platform was targeting a fourth-quarter launch but still required regulatory approval when this was reported on November 10.
Under the disclosed plan, the platform would operate as an alternative trading system. Its matching engine would use the NYSE’s existing Pillar technology; after a trade, the platform’s clearing company would settle it on an Avalanche-based ledger. Investors could fund accounts with stablecoins. Ava Labs chief business officer John Nahas said the NYSE would run a blockchain customized for regulatory requirements rather than settle on Avalanche’s public chain.
Issuance and settlement would follow different paths. The NYSE said stocks could be issued across multiple chains, while trades would be recorded and settled on its dedicated ledger. On November 2, it added Broadridge, Computershare, Equiniti and Superstate to Securitize and tZERO as transfer-agent partners. The plan covers tokens issued by custodians and by issuers themselves; according to the NYSE, both would be interchangeable with traditional shares and carry the same dividend and voting rights.
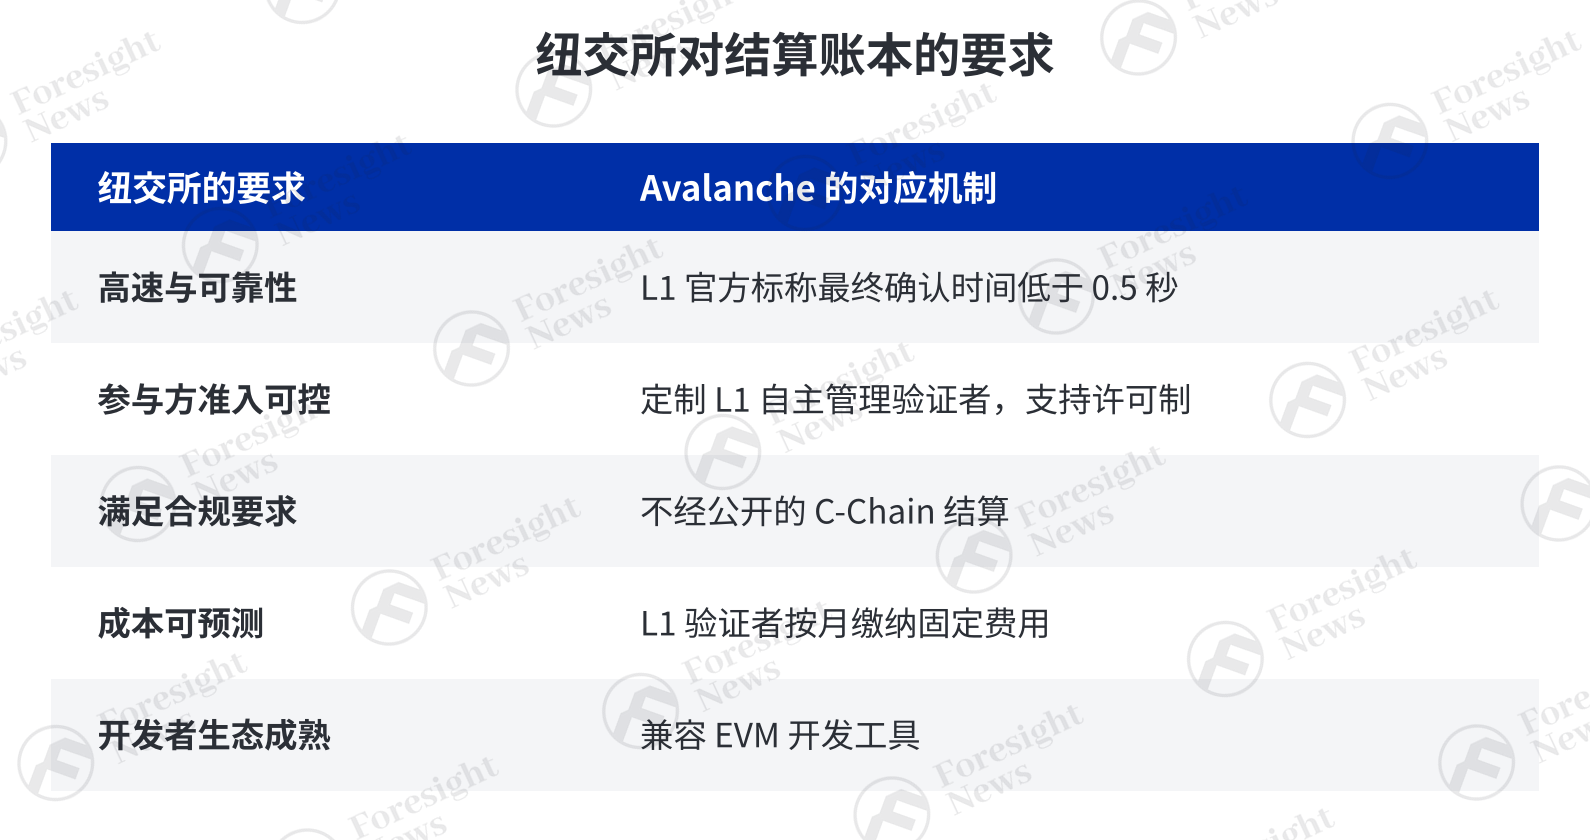
NYSE digital issuance head Dennis Lee cited speed, reliability, predictable costs, a large developer community and control over participants as reasons for choosing Avalanche. That access control is particularly relevant to securities settlement: a permissioned Avalanche L1 can manage its own validators, unlike the open C-Chain. The NYSE had announced development of the platform in January and sought regulatory approval. Although it initially described support for multiple settlement chains, its November plan specified Avalanche alone.
What the plan does—and does not—mean for AVAX
Neither the Ava Labs announcement nor the NYSE statement assigned AVAX a role in the platform’s settlement payments, transaction fees or staking. Under the existing custom-L1 model, validators pay an ongoing AVAX-denominated fee that is burned. Avalanche documentation put that fee at approximately 1.33 AVAX per validator per month when there are fewer than 10,000 L1 validators. It does not rise with the number or value of trades, and an L1 operator can choose another token for fees within its chain.
The Avalanche Foundation has acknowledged the wider gap between activity across its ecosystem and value captured by AVAX. In a July 30 research announcement, chief investment officer Matias Antonio described it as a central problem the foundation was working on. The foundation’s August 12 estimates identified C-Chain fee burns—not activity on independent L1s—as the main existing capture channel, totaling about $23.5 million since early 2024, excluding L1 validator fees. Proposals involving L1 revenue sharing and other changes remained research topics, not enacted mechanisms.
AVAX rose after the November 9 disclosure: Bitget data cited in the original report showed a high of 9.01 USDT and a price of 8.627 USDT at the time of reporting, up 6.86% over 24 hours. That market reaction should not be confused with a confirmed flow of the planned platform’s settlement revenue to AVAX. The foundation said it would track the platform’s activity and its role in the Avalanche economy; the platform itself remained subject to approval.