On November 8, 2026, Ethereum co-founder Vitalik Buterin wrote on X that he would rather treat ETH as a store of value than keep tying its worth to the idea that burned transaction fees prop up the price. The comment is a public revision of “ultrasound money,” the scarcity story that traveled with ETH for about five years: fees destroy more ETH than the protocol issues, so holders benefit as supply tightens.
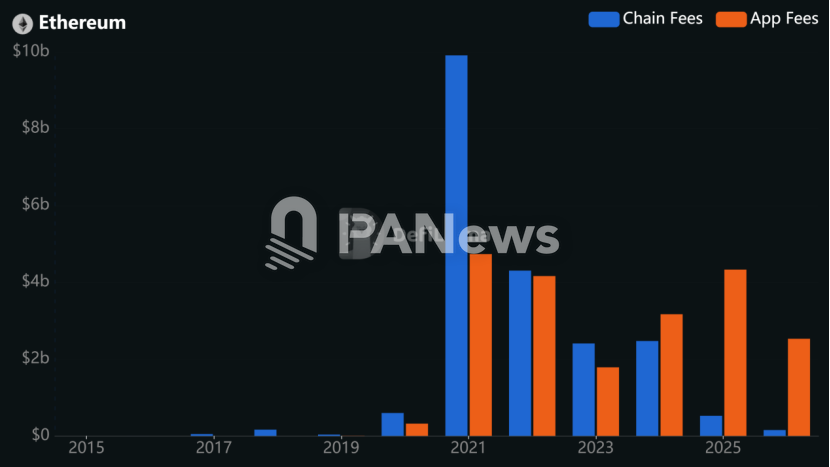
PANews writer Jae reported the remarks in an article published November 10, 2026. The piece frames a tension already visible on the network. Ethereum is processing more activity while user costs fall, yet the fees the chain collects—and therefore the ETH it burns—have shrunk.
With ETH’s market capitalization around $260 billion, Jae argues the asset is looking for a different valuation anchor. Buterin’s stated answer is store-of-value status. Under the older frame, users pay fees, the protocol burns ETH, and holders gain indirectly from greater scarcity. Under the frame he now prefers, Ethereum is secure, neutral financial infrastructure, and ETH is an asset the ecosystem is willing to hold, stake, and use over time.
Bitmine chairman Tom Lee is reported as agreeing with that shift. In his view, ETH is not a cash-flow token on the model of names such as HYPE or LIT; it is trusted collateral. A holder can stake ETH for rewards, post it in lending markets such as Aave for liquidity, and see related staked positions move into other DeFi uses. In that telling, ETH is not only a balance in a wallet. It is base collateral for on-chain finance.
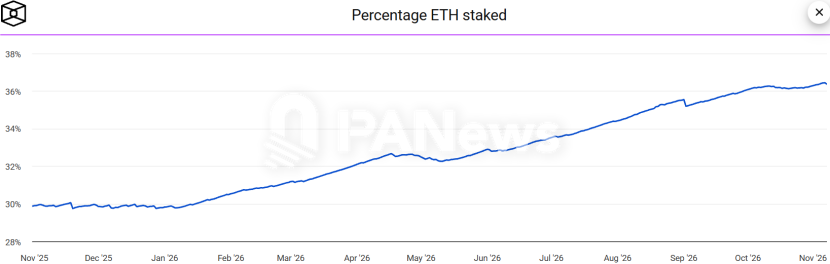
The most direct demand in this picture is staking. The Block’s figures, as cited by Jae, put staked ETH at 36.36 percent of circulating supply, compared with 29.91 percent a year earlier. A large share of tokens sits in validator duties rather than short-term trading, which the article reads as capital doing network-security work.
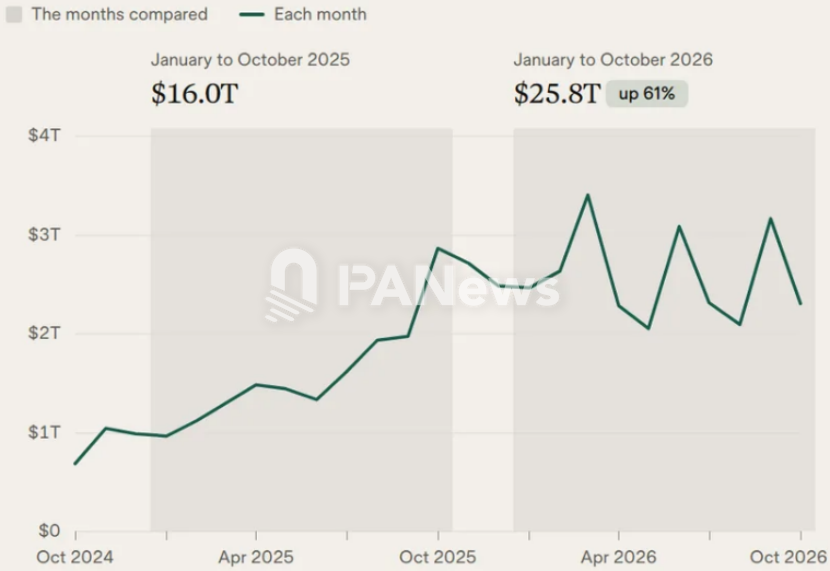
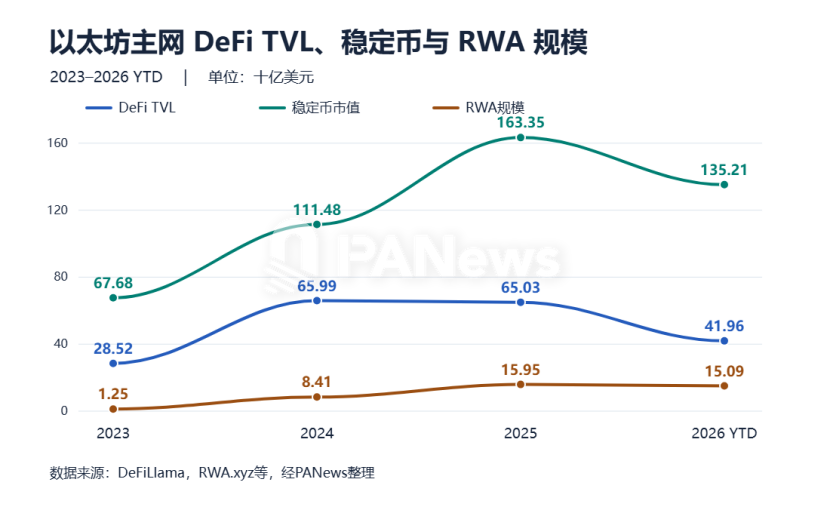
That reading still has to clear a gap between use of the infrastructure and demand for the native asset. Research attributed to Ethereum Institutional found that, in the first ten months of 2026, stablecoin transfers on Ethereum mainnet totaled $25.8 trillion, up 61 percent year over year. DeFiLlama figures cited in the same report put mainnet DeFi total value locked near $42 billion, stablecoin market value above $135 billion, and real-world-asset scale at $15 billion. Those measures show a busier settlement layer. They do not, by themselves, show continuous net buying of ETH.
Jae’s example makes the gap concrete. An institution can issue $1 billion of tokenized Treasuries on Ethereum while the collateral remains ordinary government debt, the yield comes from coupons, and settlement runs in USDC. The on-chain step needs only a small amount of ETH as gas. A larger stock of assets on the chain therefore need not become net demand for ETH. That is the hard test of a store-of-value claim: the status is not granted by announcement. ETH would have to function as base capital that on-chain finance keeps, not merely as fuel bought when someone needs to send a transaction.
Fee burns remain part of the valuation discussion even if the headline narrative moves. Jae notes that the transmission problem already shows up in how little ETH is destroyed. Buterin’s own illustration, as relayed in the article, is that a token burning $1 billion of fees a year, discounted at 4 percent, would have a theoretical present value of about $25 billion. Trading fees are not a stable cash flow, and treating a peak as the normal rate does not survive a cycle. Working backward from a roughly $260 billion market cap at the same 4 percent rate, the article says Ethereum would need to burn about $10.4 billion of fees every year to support that capitalization—far from current conditions.
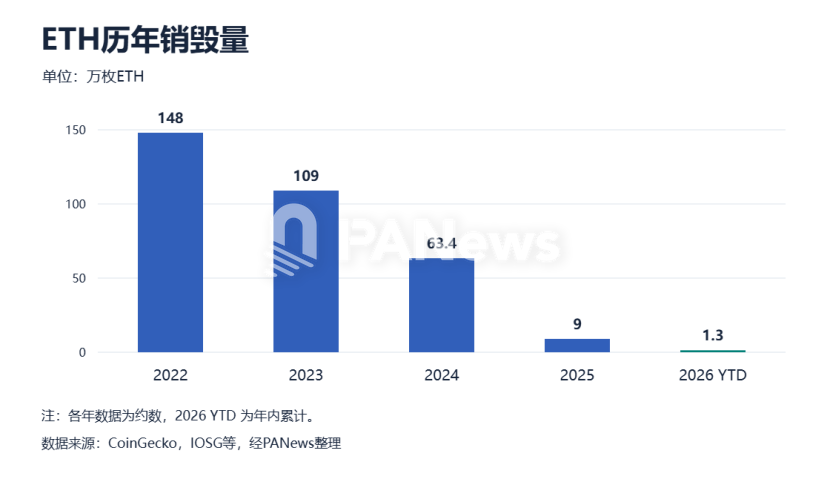
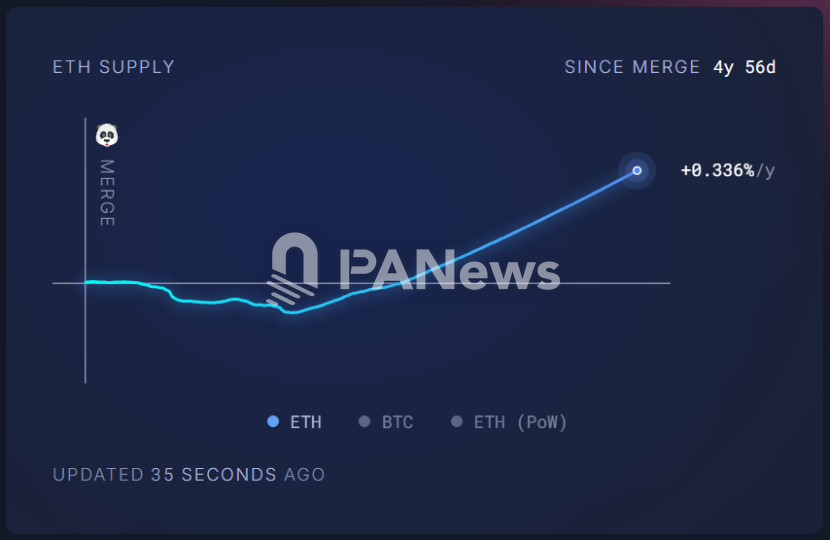
The burn totals themselves have collapsed. The system burned about 1.48 million ETH in 2022. Year to date in 2026 it had burned about 13,000 ETH, worth roughly $27.3 million at the prices used in the report, a drop of more than 99 percent by token count. ETH had already left net deflation and returned to net inflation in February 2025, with the inflation rate still rising. On those figures, the deflationary promise attached to ultrasound money had already failed.
Where the fees go has shifted as well. Treating the ecosystem as one commercial system, Jae writes that revenue has been moving from the base network toward layer-2 networks and the application layer. DeFiLlama data in the article show application-layer fees on mainnet overtaking chain-level fees as early as 2024. In 2026, mainnet fee revenue was about $152 million, while application-layer fees reached about $2.529 billion—more than sixteen times as much.
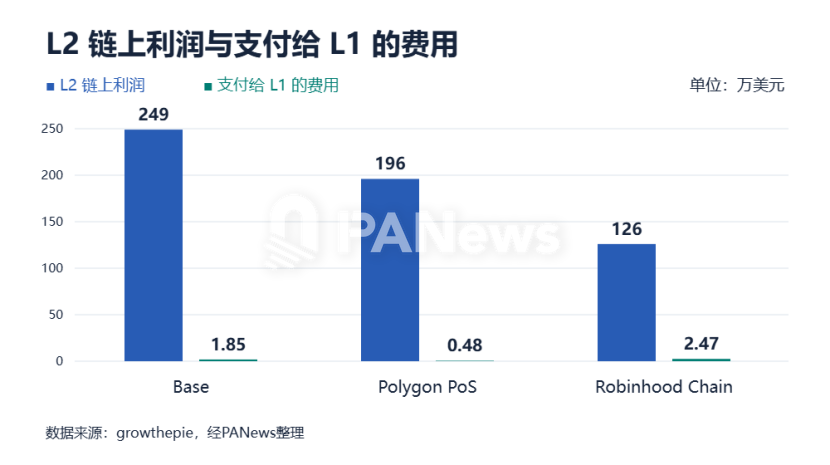
Layer 2s are the clearest case. Base settles and inherits security from Ethereum while running its own execution environment and user entry point. It charges end users, pays Ethereum for data publication and settlement, and keeps the spread as on-chain gross profit. growthepie data cited for the prior 30 days put combined on-chain profit for the top three Ethereum L2s at about $5.71 million, with Base accounting for $2.49 million. Over the same period those L2s paid Ethereum mainnet roughly $48,000 in settlement fees in total; Base’s share was about $18,500, less even than Robinhood Chain. Most of the fee value stayed on the L2. It did not reach mainnet, and it did not become a return to ETH holders.
A longer concern in the report is habit and brand. If more people complete their on-chain activity entirely on Base, Arbitrum, or similar networks and rarely touch Ethereum itself, the service they recognize belongs increasingly to the L2 and the front-end application.
Cheaper fees are not presented only as a loss. Scaling lowers the cost of a transaction. When a transfer cost several dollars, many small or frequent actions were uneconomic. At a few cents or less, uses such as high-frequency payments by AI agents, micro-transactions, and automated strategies become possible in principle. Whether that new activity grows large enough for volume to offset the lower fee per transaction is left as something still to be shown.
Lee is also quoted linking a store-of-value turn to value capture in a coming tokenization and AI cycle. That is his forecast, not a demonstrated result. Jae’s closer reading of Buterin’s post is more restrained: the high-fee path that once funded burns and supported a scarcity story is difficult to sustain, and the November 8 statement looks like expectation-setting. Rather than defend a deflation narrative that the burn data no longer support, the comment acknowledges that ETH’s value claim is moving. In the past, the network had to show it could collect enough fees to keep destroying supply. Ahead, the article says, it has to show that ETH is still worth holding even when using the network keeps getting cheaper.
Original article: PANews, November 10, 2026.